Foreclosure Timeline Cash Sale Example for NY
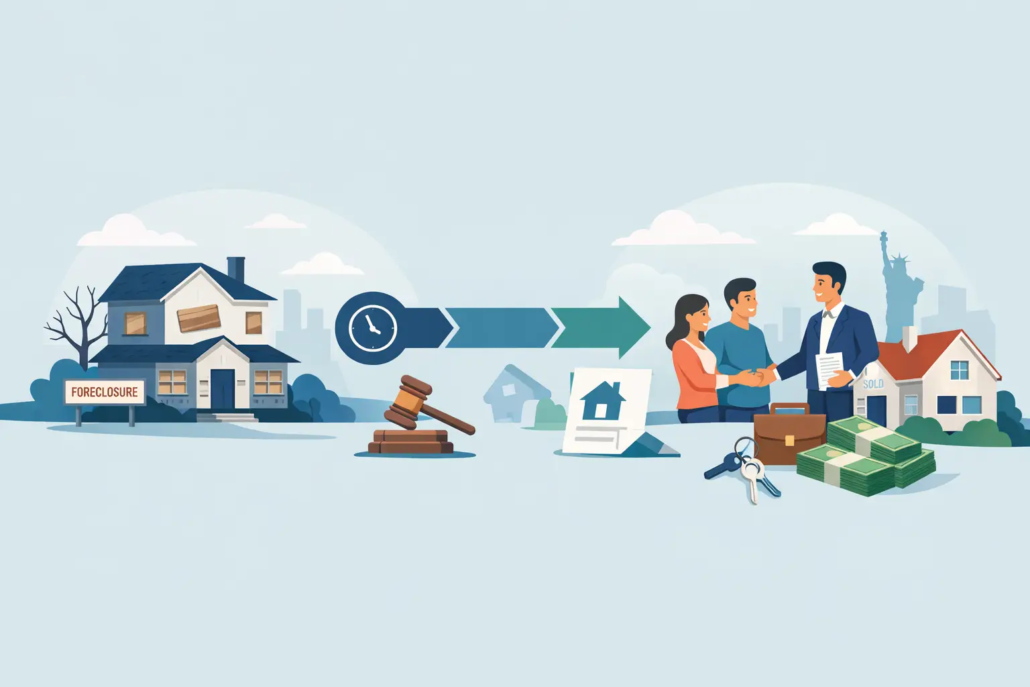
A foreclosure notice can make every day feel urgent, but you may still have options before a lender takes ownership or an auction is held. This foreclosure timeline cash sale example shows how a New York homeowner could sell an as-is property for cash while there is still time to resolve the mortgage debt and avoid a foreclosure sale.
The exact dates vary by loan, lender, court schedule, and property circumstances. New York has a judicial foreclosure process, which often takes longer than homeowners expect. Still, waiting for the last possible moment can reduce your choices. A cash sale works best when you start the conversation early, verify the payoff amount, and choose a closing date that fits the deadline.
A Foreclosure Timeline Cash Sale Example
Consider a homeowner in Queens who falls behind after a job loss. Their mortgage payment is $3,200 per month. They miss payments, receive lender notices, and eventually face a pending foreclosure case. The home needs work: an aging roof, outdated kitchen, and some water damage in the basement. Listing it with an agent would likely mean repairs, cleanout work, inspections, showings, and uncertainty about whether a financed buyer can close.
A direct cash buyer can offer a different path. Rather than fixing the house or putting it on the market, the owner requests a fair and honest cash offer, reviews the numbers, and closes before the foreclosure reaches its final stage.
Month 1: The first missed payment
After the first missed payment, the lender typically contacts the homeowner by phone, mail, or email. Late fees may be added, and the missed payment is reported according to the lender’s practices. At this point, foreclosure has not begun, but the situation should not be ignored.
The homeowner may be able to catch up, request a repayment plan, apply for loan modification, or sell the property. If selling is the right choice, this is usually the strongest time to act. There is more room to compare options, gather paperwork, and set a closing date without a court deadline controlling every decision.
Months 2 to 3: Default notices and growing pressure
As missed payments continue, the total needed to bring the loan current increases. The homeowner may receive formal notices of default, loss mitigation information, and warnings that foreclosure could follow. Calls and letters become more frequent.
In this example, the homeowner realizes that catching up is not realistic. The mortgage arrears, late charges, property taxes, and repair needs have become too much. They ask for a cash offer on the home as-is.
A reputable direct buyer reviews the property condition, local sales, and the seller’s timing needs. There should be no pressure to accept an offer. The homeowner should also ask for a mortgage payoff statement from the lender, which shows the amount required to pay off the loan by a specific date.
Months 4 to 6: Foreclosure may formally begin
In New York, the lender generally must follow pre-foreclosure notice requirements before filing a foreclosure lawsuit. Once a case is filed and served, the homeowner has legal deadlines and should read every document carefully. A housing counselor or foreclosure defense attorney can help explain available rights and options.
A pending case does not automatically mean the home cannot be sold. In many situations, the owner still holds title and can sell before the auction or other final transfer of ownership. The key is making sure the closing happens in time and that the sale proceeds are enough to satisfy the mortgage payoff, liens, taxes, and closing obligations.
In our example, the homeowner receives a cash offer of $585,000. The current mortgage payoff is $492,000. There is also $8,000 in unpaid property taxes and water charges. After those obligations are paid, the homeowner can receive the remaining proceeds, subject to the final title review and settlement figures.
How a Cash Closing Can Fit the Timeline
The owner accepts the offer after reviewing the terms. The buyer purchases the house as-is, so the owner does not need to replace the roof, renovate the kitchen, remove every unwanted item, or prepare for inspection demands. A title company or closing attorney checks the title, confirms liens, and coordinates the payoff with the lender.
If the title is clear enough to close and all parties respond promptly, a cash sale may close in as little as seven days. Some situations take longer, especially when there are estate issues, judgments, open permits, bankruptcy filings, tenants, or multiple owners who need to sign. The right closing date is not always the fastest one. It is the date that resolves the problem before the foreclosure deadline while giving the title work time to be completed correctly.
At closing, the buyer’s funds are used to pay the mortgage lender and other approved charges. The seller signs the required documents, transfers ownership, and receives any remaining proceeds. The foreclosure case may then be discontinued or otherwise addressed after the lender confirms it has been paid. Do not assume this happens automatically. Keep copies of all payoff and closing documents and confirm that the lender updates its records.
When Selling for Cash May Not Solve Everything
A cash sale can stop a foreclosure from moving forward when the sale closes before the property is sold at auction and the proceeds cover what is owed. But every case has details that matter.
If the home is worth less than the total mortgage balance and liens, the seller may need lender approval for a short sale. If an auction date is already scheduled, there may be very little time to complete title work and close. If bankruptcy has been filed, the sale may require court involvement or legal guidance. A homeowner facing a completed foreclosure or an eviction notice may have different options than someone who has only recently missed payments.
That is why an honest buyer should never promise a result without first understanding the timeline, payoff amount, property condition, and title situation. A fast offer is useful only when it comes with clear terms and a realistic plan to close.
What to Gather Before Requesting an Offer
You do not need to have every document perfectly organized to ask for a cash offer. However, having a few basic items can help move the process faster. Keep the latest mortgage statement, foreclosure notices, tax bills, and any information about liens or judgments nearby. If there are other owners, heirs, or a spouse on title, identify them early.
Be straightforward about property issues too. Fire damage, code violations, tenants, inherited belongings, or needed repairs do not necessarily prevent a cash sale. They do affect the offer and the closing plan. Clear information helps prevent last-minute surprises.
Do Not Wait for the Auction Date
The biggest mistake in a foreclosure situation is often assuming there is no point in acting until the lender gives a final date. The earlier you explore a sale, the more control you may have over the outcome. You can ask questions, review the offer, speak with an attorney or housing counselor, and decide whether selling is better than trying another solution.
For New York homeowners who need certainty, a direct cash sale can remove many of the barriers that delay a traditional listing: no repairs, no open houses, no buyer financing contingency, and no agent commissions. Nationwide Homes 4 Sale can review your property, explain a straightforward cash offer, and work toward a closing schedule that matches your situation.
If foreclosure pressure is building, start by finding out your payoff amount and your next legal deadline. Then evaluate your real options while there is still enough time to choose the one that gives you the clearest path forward.

Leave a Reply
Want to join the discussion?Feel free to contribute!